
Craig Rickman crunches some numbers and explores what it may take to amass a seven-figure, tax-efficient pot by the time you reach age 67.
Many investors dream of the day that they log in to their online investment account and see a seven-digit sum.
Not only is there the fulfilment that comes with having squirrelled away a million quid, but, unless your lifestyle is particularly lavish, it could be your ticket to financial freedom.
Reaching this lofty milestone is unlikely to happen overnight – unless you receive a sizeable and unexpected windfall – but it’s certainly not out of reach.
According to estimates, more than a million savers are sitting on seven-figure pensions, while there are over  4,000 individual savings account (ISA) millionaires.
Whether you have £1 million in a pension, ISA, or both, it’s an envious position to be in. And using a combination of the two tax wrappers can be prudent. Each offers different tax advantages and access rules, which can give you the best of both worlds when saving and investing for your long-term future.
How can I get to £1 million by age 67?
There are several factors that will determine how quickly you can amass a seven-figure portfolio. These include how much you’ve saved already, your time frame, what you can afford to stick away every year, and how your investments perform.
So, let’s crunch some numbers, based on saving £500 a month.
The table below shows whether you might be on track to build a £1 million portfolio by age 67. Just find your age on the top row, then how much you’ve tucked away already in the left-hand column – the cell where they meet shows the amount you might expect given our assumptions.
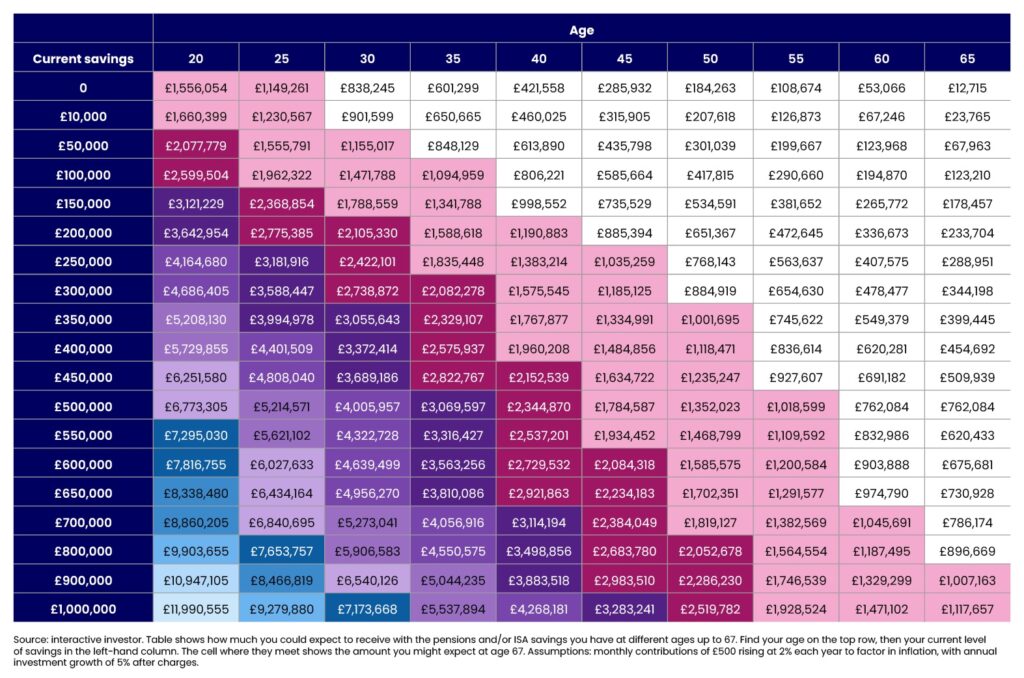
I’ve chosen a monthly contribution of £500 as it should be palatable for most investors, but for those worried it might be a stretch too far, it’s worth noting that this figure includes money from third parties, such as upfront pension tax relief and employer pension contributions.
The thing that really leaps out from this table is the importance of time. The difference between starting the savings process when you’re age 20 or 30 is a whopping £700,000, highlighting the powerful nature of compound returns.
It also shows the merit of doing what you can to build a healthy savings pot by the time you reach middle age. A 45-year-old who’s already tucked away £250,000 could get to around £1 million in 22 years’ time based on our assumptions.
The figures should also offer some optimism to those who feel it’s too late to make a difference. Even if you’ve hit age 40 with little to no savings, by committing to £500 a month you could still build a pot of £400,000 by age 67, while a 50-year-old could amass £184,000. These may not be seven figure sums but will vastly improve your lifestyle in old age.
Make sure you consider inflation
The threat that inflation poses to our money has been illuminated in the past few years. This has been an unusual period, to put things mildly, but over the course of your lifetime even small annual increases in prices can mount up over time.
For instance, if you’re 20 years old, a £1.5 million pot portfolio at age 67 won’t have the same buying power as it does today. It will erode in real terms. If you’re closer to later life, the less impact inflation will have. But whatever your age, it’s important to factor in future price rises.
What I should I think about when choosing between pensions and ISAs?
Using both pensions and ISAs can be a great way to build a £1 million portfolio, but you don’t have to use them in equal measure. While there are no set rules on how to split contributions, here are a few things to consider.
- Get an upfront boost where you can
As noted above, you get upfront tax relief on anything you pay into a pension at your marginal rate, so long as it’s within the lower of 100% of earnings or £60,000. This can provide a big help to propel you towards the seven-figure target.
If you make personal contributions, such as to an ii self-invested personal pension (SIPP), you’ll get an immediate upfront 25% boost from the government, and you can claim back any extra if you pay either 40% or 45% tax.
In short, if you’re a higher-rate taxpayer, a £500 pension contribution will ultimately cost you just £300.
Employees get extra support, in the shape of workplace pension contributions. Provided you pay 5% of qualifying earnings (between £6,240 and £50,270), your employer must pay at least 3% – valuable free money to set you on the path to a financially comfortable future. And some businesses are more generous and will offer to contribute more.
Alternatively, if you’re an owner/director of a private limited company, you have the option to make contributions via the business. These are typically deemed an ‘allowable business expense’, so can offset your corporation tax bill. And you planned to draw that money as salary you’ll also save 15% in employer national insurance.
- Use ISAs for access
The upfront tax breaks of pensions are clearly valuable, but there are some things to be aware of.
While pensions and ISAs both sit within the “tax wrapper” banner, they have contrasting rules regarding tax and access. In simple terms, with pensions you get tax relief on the way in but withdrawals (other than 25% which you can usually draw tax free) are taxable. With ISAs, the situation reverses: you don’t get upfront relief, but withdrawals are tax free.
The access rules also differ. You can encash ISA money whenever you like but can’t touch your pensions until age 55 (rising to 57 in 2028).
It’s important to factor these rules into your plan, as there might be instances where you need or want to draw from your investment portfolio sooner. This may include things such as buying a home, jetting off on nice holidays or supporting children through education.
We also can’t ignore the unexpected events that life has a habit of throwing up. Losing a job or the death of a loved one could trigger a need to access your investments and may also restrict your scope for long-term saving during certain periods. And that’s OK – just try and get back on track as soon as you can.
The accessibility of ISAs is also key if you plan to retire early.
Let’s say you aim to pack up work at 53. Although you won’t be able to access your pensions at this point, you don’t have to rip up your plans. You will, however, need funds to fill the gap until you can draw from them. ISAs are your friend here.
By the same token, you should dip into your portfolio only when absolutely necessary as the less you draw, the quicker you’ll get to the £1 million holy grail.
Focus on your personal goals
While £1 million is a nice round figure to aim for – and one that would likely secure your financial future – I’ve purely used this amount as a gauge to show how you can build future wealth, without sacrificing everything today.
A more appropriate approach is to focus on and save towards the financial goals you want to achieve during your lifetime, which may be more expansive and nuanced than purely amassing a sum of money to draw from down the line.